
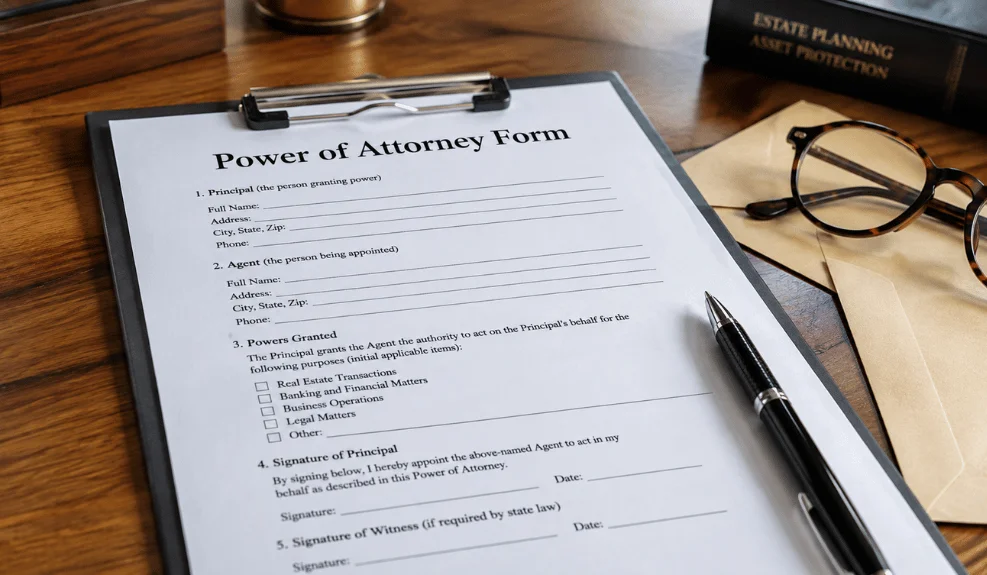
A power of attorney form lets you appoint an agent to act for you, but one U.S. document does not fit every state or purpose. Choose the form based on the state and the authority you want to grant, then follow that state’s rules for signatures, witnesses, notarization, and any special filing or recording requirements.
The biggest mistake is downloading the first generic PDF you find. Start with two questions instead: What do you want your agent to do, and which state’s law applies?
| Your need | Document to consider | Key point |
|---|---|---|
| Ongoing financial management | Durable financial POA | Can remain effective during incapacity if properly drafted |
| Broad financial authority while capable | General POA | Grants broad powers, but state law may limit them |
| One transaction or defined task | Limited or special POA | Gives the agent only the authority you specify |
| Healthcare decisions | Medical POA, healthcare proxy, or advance directive | Terminology and execution rules vary by state |
| Representation before the IRS | IRS Form 2848 | Federal tax authorization has its own form and rules |
| Managing Social Security or SSI payments | Representative payee appointment | A regular POA does not make the agent an SSA payee |
Cornell Law explains that the person creating the document is the principal. The person receiving authority is often called the agent or attorney-in-fact. That agent does not need to be a lawyer.
TL;DR: Pick the state first, then choose the authority you need. Decide whether the document must remain effective during incapacity. Name a trustworthy agent and a backup. Follow the exact witness and notary rules. Check whether a bank, government agency, healthcare provider, or property transaction requires a separate form to be completed before signing.
How to Choose a Power of Attorney Form
Start with the job you need someone else to perform. A POA that is suitable for selling one vehicle may be a poor choice for long-term financial planning. A general authorization can give an agent broad financial powers. Cornell notes that even broad authority can still be limited by state law or court decisions.
A limited authorization narrows the agent’s role. You might use one for a particular property transaction, account, contract, or period. State witness and notarization requirements still apply.
A durable financial authorization is designed to continue after incapacity, provided its duration is properly stated. A non-durable version generally ends if the principal loses capacity. Specific rules vary by state.
Healthcare documents work differently. A state may use terms such as medical POA, healthcare proxy, healthcare agent, or advance directive. Their purpose is to authorize medical decisions when the principal cannot make or communicate those decisions.
Those state-by-state differences are why a form should never be chosen by title alone.
What Information Should the Document Include?
A useful POA needs enough detail to show who has authority, what that authority covers, and when it applies.
Check the document for:
- The principal’s full legal name and identifying details.
- The agent’s full legal name and contact information.
- A successor agent in case the first choice cannot serve.
- A clear description of the powers being granted.
- Any powers that are specifically excluded.
- The effective date or triggering event.
- Language addressing durability, if that is intended.
- Any expiration date or transaction-specific end point.
- Required signatures, witnesses, acknowledgments, and notarization.
The document should be specific about sensitive powers. Gifts, beneficiary changes, business interests, trusts, real estate, and transfers to the agent can raise additional legal issues.
Estate documents also need to work together. BritLegal’s guide to beneficiary designations and inheritance shares shows how separate beneficiary paperwork can control what happens to certain assets after death.
Choose the Agent as Carefully as the form.
The agent may receive access to bank accounts, investments, contracts, property, and personal financial information. Convenience should not be the only reason you choose someone.
Cornell describes an attorney-in-fact as a fiduciary of the principal. The Consumer Financial Protection Bureau also publishes current guidance for people managing another person’s money under this type of appointment.
A suitable agent should be organized, trustworthy, willing to keep records, and able to keep the principal’s money separate from their own.
Consider naming a backup as well. Doing so can prevent the document from becoming unusable if the first agent dies, becomes ill, resigns, or refuses to act.
For larger estates, review the appointment alongside other ownership and transfer arrangements. BritLegal’s property and estate disposition explainer provides related background on how assets may be transferred or otherwise dealt with legally.
Signing Rules: Witnesses, Notaries, and State Law
There is no universal U.S. signing rule for every POA.
States may impose requirements involving witnesses, notarization, statutory language, acknowledgment clauses, or specific forms. Cornell specifically notes that jurisdictions can impose special requirements on a POA’s form and substance.
That means you should not copy a signature page from another state.
Before signing, check:
- Your state’s current statute or official form.
- Whether witnesses are required.
- Whether a notary is required.
- Whether certain people are barred from serving as witnesses.
- Whether the document must be recorded in connection with a planned real estate transaction.
- Whether the institution receiving it has its own acceptance procedure.
Complete these checks before everyone signs. Fixing an execution problem after the principal has lost capacity can become much harder.
When Does the Authority Start and End?
The effective date depends on the document and state law.
Some authorizations take effect as soon as they are properly executed. Others may be written to take effect after a specified event. State rules determine whether and how that type of future-triggered authority works. Durability is a separate issue. Cornell explains that a properly durable authorization can continue during the principal’s incapacity. A non-durable one generally does not.
A durable appointment does not continue after the principal dies. Cornell describes durable authority as generally lasting until death or revocation. After death, authority over estate property generally shifts to an executor, administrator, trustee, or another legally recognized successor, while some assets may pass according to beneficiary arrangements.
Some Government Agencies Require Their Own Authorization
A broad financial POA does not automatically replace every agency form. For federal tax matters, the IRS uses Form 2848, Power of Attorney and Declaration of Representative. The IRS says that the form authorizes an eligible individual to represent a taxpayer before the agency and can permit access to confidential tax information.
The IRS also provides its own submission procedures for these authorizations. Social Security provides another important exception. The SSA states that holding a power of attorney does not make someone a representative payee. A person who needs to manage another beneficiary’s Social Security or SSI payments must apply for and be appointed to that role.
This distinction is easy to miss if you rely on a generic legal template.
What Does a POA Form Cost?
The document itself can cost $0 when you use a free form provider or another no-cost source. Current form sites advertise free state-specific samples and PDF or Word downloads.
Extra costs can arise from:
- Notarization.
- Paid document-preparation services.
- Attorney review or custom drafting.
- Recording fees for documents connected with certain property transactions.
- Certified copies or other institution-specific requirements.
A free template can be a useful starting point. It is not proof that the document meets your state’s current execution rules.
If the powers are broad or the estate is complicated, the cost of a legal review may be easier to justify than the cost of repairing a defective document later.
When a Generic Template Is Not Enough
Simple situations are easier to handle with standardized forms. Complexity changes the calculation.
Consider professional review if the agent will have authority involving the following:
- Major gifts or transfers to family members.
- Trust creation, amendment, or funding.
- Business ownership or closely held companies.
- Large real estate transactions.
- Medicaid or long-term care planning.
- Conflicts among children, spouses, or potential agents.
- An agent who may benefit from transactions they approve.
- Property or financial affairs in several states.
BritLegal’s legal advice library can help you identify related issues before you decide whether professional advice is needed.
Common Mistakes to Avoid
Using the wrong state’s document. A polished PDF can still fail if the document’s signing requirements do not match those of the governing state.
Giving more authority than necessary. If an agent only needs to complete one transaction, a limited appointment may reduce unnecessary access.
Ignoring durability language. If incapacity planning is the goal, make sure the document addresses whether the authority continues after incapacity.
Choosing an agent without discussing the role. Ask first. The person should understand the responsibilities and know where the relevant records are stored.
Assuming one document works everywhere. The IRS and Social Security examples show why specialized government rules matter.
Keeping outdated copies in circulation. If you replace or revoke an appointment, consult a lawyer about the required steps in your state and notify the relevant institutions.
Your Next Step
Get started by identifying your state and the exact job you want the agent to perform. Then check whether your state publishes a statutory form and confirm the current execution rules before signing. Some appointments are worth a second opinion: gifts, trusts, business interests, major real estate transactions, or complicated family arrangements.
In those cases, use BritLegal’s Find a Lawyer section to continue your research, then get advice from a lawyer licensed in the relevant state.
Frequently Asked Questions
No universal document is guaranteed to meet every state’s rules. States can impose different requirements for language, witnesses, notarization, and particular powers. Use a form designed for the state whose law governs the document.
Not every state or document uses identical formalities. Some require notarization, some require witnesses, and some situations can involve both. Check the current requirements for your state and document type before signing.
Durability means the authority can continue if the principal later becomes incapacitated. The document must satisfy the relevant state requirements for durable authority. Cornell notes that the durable character must be expressly established.
An attorney-in-fact does not need to be a lawyer. Whether you should hire legal counsel depends on the powers involved, state law, and the complexity of your finances or estate.
A principal who still has the legal capacity required by state law can generally revoke an appointment in accordance with applicable state procedures. Durable authority may also end at death. Ask about written notice, old copies, and institution-specific procedures.
Not by itself. The SSA requires a separate representative payee appointment for someone who will manage another person’s Social Security or SSI payments.